Specialized dwelling fire (DP-3) coverage protecting rental real estate, rental income cash flows, and investor liability across the United States.
Renting out residential real estate introduces legal exposures and property perils that standard homeowners policies explicitly exclude.
When a property is occupied by tenants rather than the homeowner, insurance carriers classify it as a commercial rental exposure. Landlord policies (commonly written on DP-3 Dwelling Fire forms) are tailored to cover the physical building, landlord-owned equipment, tenant slip-and-fall liability, and the lost cash flow if covered disaster repairs force tenants to vacate.
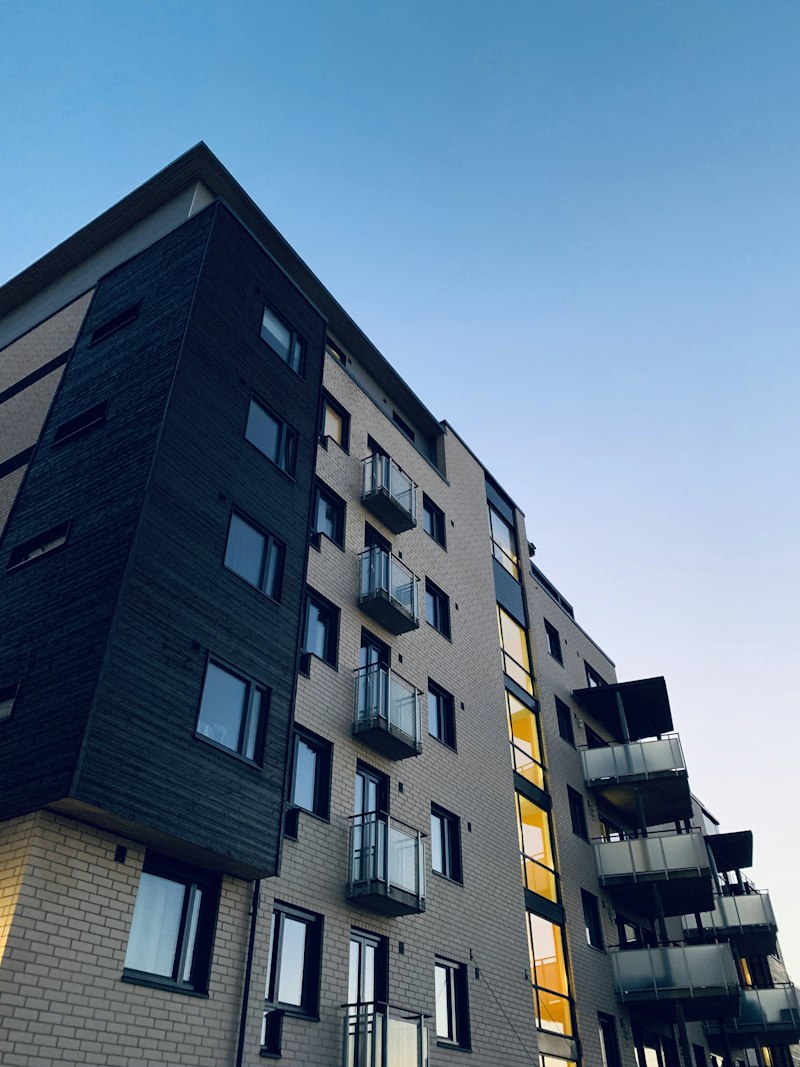
A comprehensive landlord insurance policy combines structural damage defense with operational business protection.
Covers the physical rental home structure, roof, foundation, walls, plumbing, and HVAC systems against fire, lightning, wind, hail, and vandalism. On DP-3 policies, coverage is written on an open perils basis.
If a major covered loss (such as a fire or severe winter freeze) causes tenants to move out while contractors repair the property, this coverage reimburses the lost rental income so you can keep paying your mortgage and property taxes.
Protects property owners from costly legal defense costs and medical payouts if a tenant or guest suffers an injury on the rental premises (e.g., icy walkways, stairway handrail failures) and alleges property negligence.
Failing to switch from a homeowners policy to a landlord policy when leasing a property is one of the most common and disastrous mistakes property investors make.
Standard homeowners insurance policies contain explicit owner-occupancy clauses. If an insurer discovers that you leased the property without notifying them, they have the legal right to void the policy and deny entire five-figure claims.
Landlord policies only cover furnishings provided by the landlord (like refrigerators, laundry units, or lawnmowers). Tenants must be advised to secure their own separate HO-4 renters insurance policies to protect their clothing and belongings.
Most landlord policies contain vacancy exclusions: if the rental property sits unoccupied for longer than 30 to 60 consecutive days between tenants, protections against vandalism and pipe freezing may be suspended unless a vacancy endorsement is secured.